The AI Index 2026 Readiness Gap: Why Real Estate Finance Needs Better Measurement

Agentic Assets Research Team
Corbis Research
April 14, 2026
8 min read
The Artificial Intelligence Index Report 2026 is long, but one message is simple: AI capabilities are accelerating faster than the systems built to measure, govern, and evaluate them. That readiness gap is not abstract. It is exactly the gap commercial real estate and finance teams face when they try to use AI for underwriting, research, portfolio surveillance, and investment memos.
In real estate finance, the problem is rarely that teams lack documents. They have too many: broker decks, leases, rent rolls, loan agreements, appraisals, zoning memos, environmental reports, market research, and emails. The hard part is converting that document pile into traceable claims. AI can help, but only if the workflow tracks sources, versions, assumptions, and uncertainty.
Benchmarks are not operating controls
A model that performs well on public benchmarks can still fail in a real estate workflow. A benchmark may test reasoning or retrieval, but a live underwriting process tests permissions, freshness, document quality, local market nuance, and accountability. A model may summarize a lease accurately but miss that the uploaded version is outdated. It may answer a market question fluently but cite a report that predates the most recent rate move.
That is why AI readiness in CRE should be measured at the workflow level. Can the system identify which sources it used? Can it distinguish public data from proprietary data? Can it flag stale evidence? Can it show which assumptions changed between investment committee drafts? Can a senior professional reproduce the answer?
Data infrastructure is the bottleneck
The AI Index emphasizes that the infrastructure around AI matters. For CRE, this means normalizing property, tenant, market, loan, and document data into forms that can be retrieved and audited. Retrieval-augmented generation helps only when the retrieval layer is curated. If the corpus is a folder of inconsistent PDFs, AI becomes a better search box, not a reliable decision system.
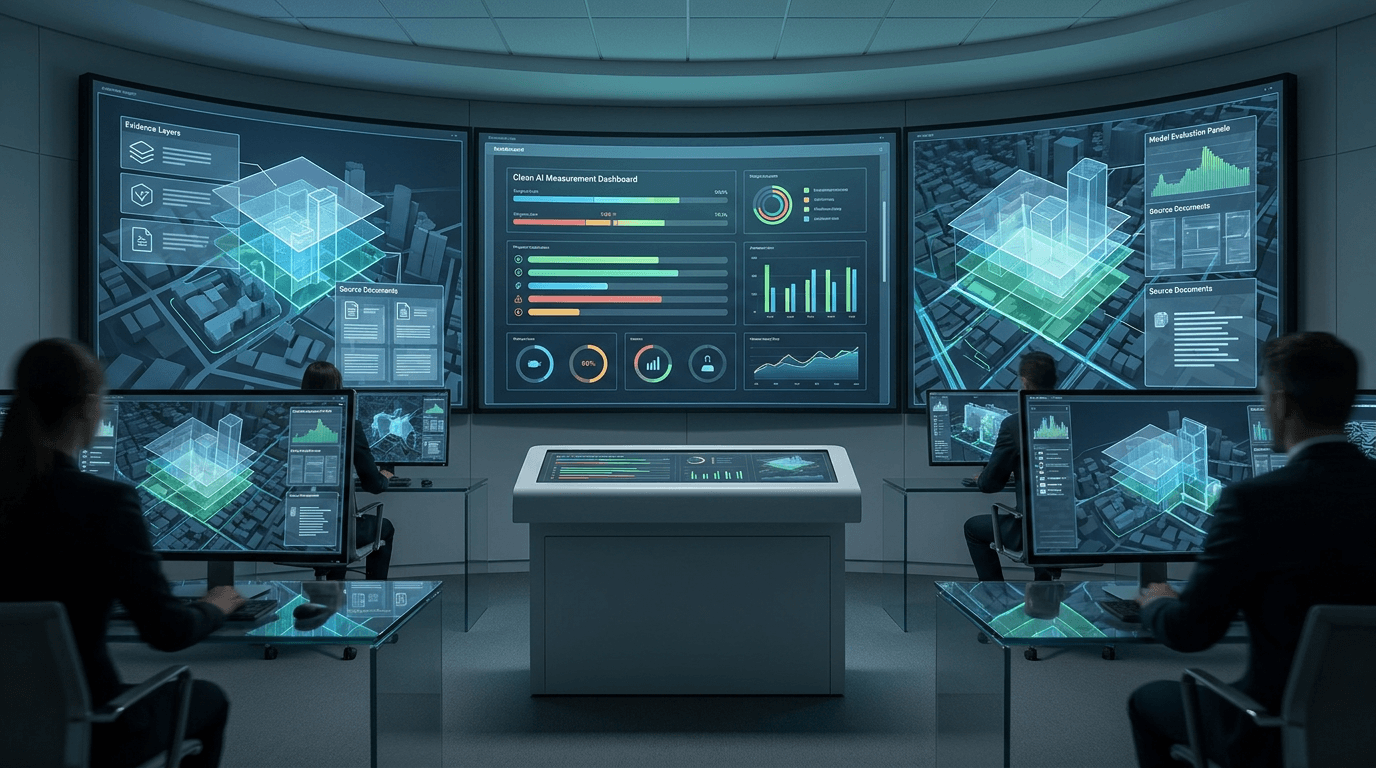
The practical path is to build evidence layers: one layer for documents, one for extracted facts, one for market data, one for model assumptions, and one for human approvals. AI agents can then operate across those layers with better constraints. That is more valuable than asking a general model to improvise a complete answer from scattered context.
Readiness is organizational
Technical capability is only one part of readiness. Teams need rules for when AI can draft, when it can act, when it needs approval, and when it must cite. They need review patterns that treat AI output as a hypothesis, not a conclusion. They need vendor discipline, because model concentration and third-party dependency are financial risk issues, not just procurement issues.
The real estate firms that benefit most from AI will not be the ones with the most demos. They will be the ones with the best measurement. They will know how often agents are used, which tasks they improve, where errors occur, which sources drive decisions, and whether the final recommendation changed after human review. In 2026, that is what AI readiness looks like.
Readiness is an operating metric
The AI Index is valuable because it separates capability growth from adoption capacity. CRE finance needs the same separation. It is easy to say that models are improving. It is harder to measure whether an investment team has clean data, permissioned workflows, evaluation sets, source capture, and reviewer habits. Without those operating metrics, AI adoption becomes a collection of demos. The Stanford AI Index is a useful external benchmark because it tracks capability, investment, policy, and adoption signals in one place rather than treating AI progress as a single model leaderboard.
The NIST AI Risk Management Framework gives a useful vocabulary: govern, map, measure, and manage. In CRE, those verbs translate into practical controls. Govern who can use AI on deal files. Map which workflows contain confidential data. Measure whether AI outputs are correct and cited. Manage failures with escalation and review. The NIST generative AI profile adds more concrete risks around provenance, harmful output, information integrity, and human oversight.
What CRE firms should benchmark
- Data readiness: document coverage, metadata quality, and source recency.
- Workflow readiness: repeatable tasks with clear inputs and outputs.
- Risk readiness: approval paths, audit trails, vendor review, and incident handling.
- Commercial readiness: whether AI improves speed, coverage, conversion, or investment quality.
The market will not reward AI theater for long. The durable advantage is measured capability: systems that make teams faster while leaving better evidence behind.
Share this article
Related Articles
The EU AI Act Timetable Moved. The Work in Real Estate Lending Did Not.
A July 2026 regulation pushed the AI Act's high-risk obligations to December 2027. For lenders using AI near a credit decision, the deferral changes the deadline, not the evidence a supervisor will ask for.
Beyond the Model Inventory: Governing Agentic AI Vendor Dependencies
The latest financial-sector guidance does not treat agentic AI as an ordinary model. That makes a narrow model inventory insufficient. Firms need an inventory of the system, its permissions, evidence path, external dependencies, and workable exit plan.
RAG Evaluation Is Model Risk Management for Financial Research
Retrieval helps financial AI systems cite sources, but it does not remove model risk. Finance teams need evaluation loops that test retrieval quality, citation fidelity, and reviewability before they rely on generated research.